Buffett's textile lesson applied to Ethan Allen: why we recommend voting FOR all five DGB nominees on the WHITE card.
Published on
October 21, 2026
Commodity businesses are very hard to win in. Unfortunately, the furniture business is largely commoditized. When buyers see little difference between products, the lowest bidder sets the price.
Ethan Allen is a 94-year-old furniture maker that faces increasing competition, poor stock returns, and a proxy contest. Our assessment concludes that management leaves room to be desired. Egan-Jones recommends that shareholders vote FOR all five dissident nominees on the WHITE card at the November 4 annual meeting.
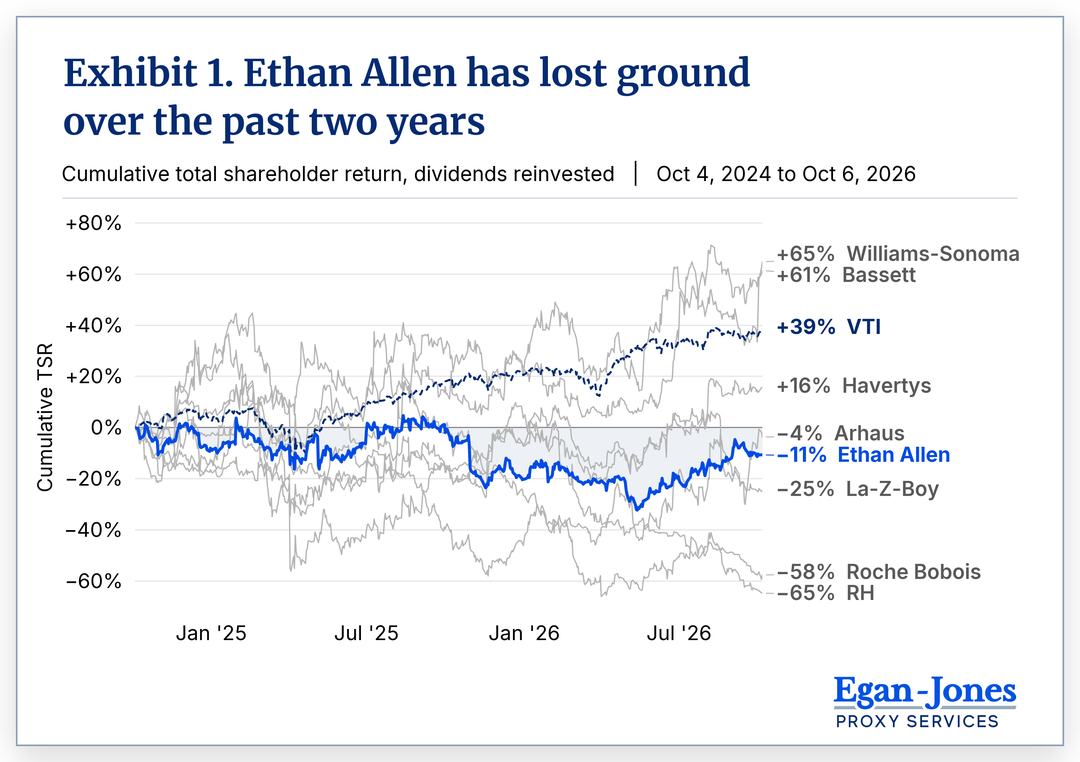
Source: daily adjusted closing prices (Yahoo Finance), dividends reinvested. Bassett, Havertys, Arhaus, La-Z-Boy and RH are from the Ethan Allen fiscal 2026 compensation peer group; Williams-Sonoma and Roche Bobois are added for comparison. Roche Bobois is measured in euros. The broad market is the Vanguard Total Stock Market ETF (VTI).
Buffett’s textile lesson
Buffett took control of Berkshire Hathaway in 1965, when it was a New England textile maker, and kept the mills running for twenty years.
Berkshire closed the textile business in 1985. Looms it had bought for $5,000 apiece in 1981 sold for scrap at $26 each, and Buffett wrote that he should have quit sooner.1 In 2010 he told CNBC it took him twenty years to give up on textiles, and he reckoned Berkshire would be worth about $200 billion more had he started with an insurance company.2 His advice:
Buffett's 1985 letter explains why the mills failed. Whenever new equipment promised lower costs, Berkshire's competitors bought it too, and the savings turned into lower prices across the industry, while the world kept far more textile capacity than it needed.1 Five years later, writing about the airline business, he stated the general rule:
“[In a commodity business,] it’s impossible to be a lot smarter than your dumbest competitor.”
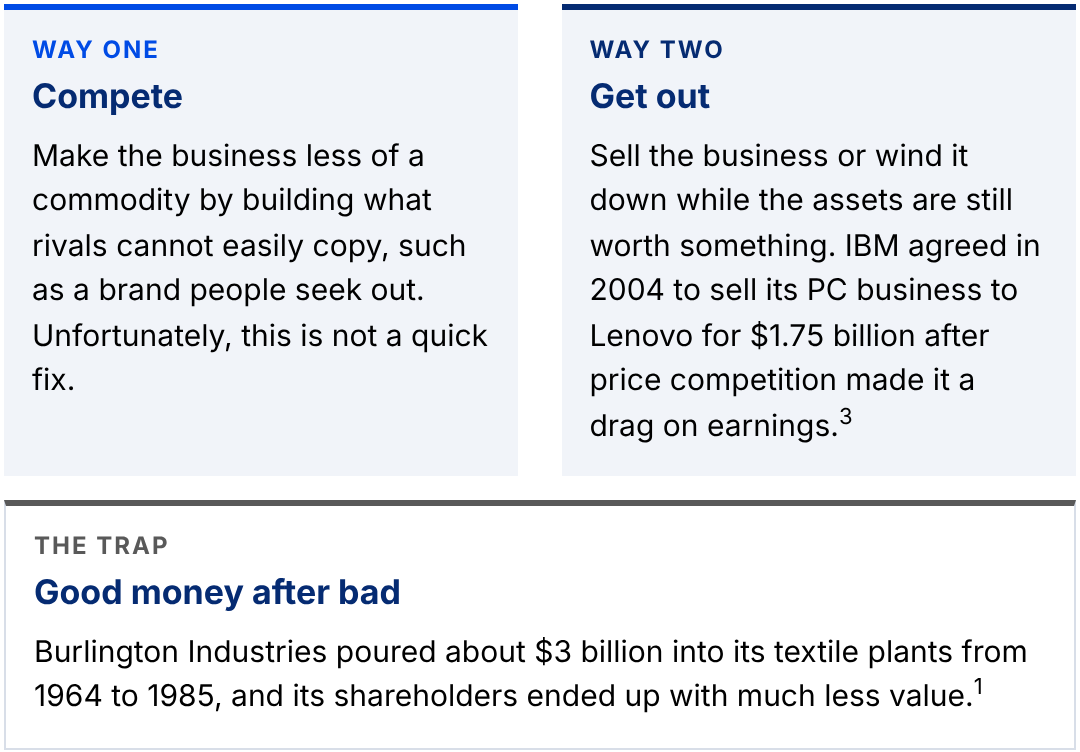
A company stuck in a business like this has two sensible choices.
Furniture Fatigue
As we stated earlier, the furniture market is highly commoditized. This presents firms in the industry with a few challenges, especially at the low and middle ends of the market.
Product differentiation is lacking. Designs can be easily copied by competitors. Some websites exist primarily to find cheaper alternatives to furniture.
RELATEDLY, low brand recognition. Unlike other markets (e.g., fashion, vehicles, consumer goods), brand recognition is low, thereby removing an opportunity to price based on brand.
THUS, pricing power is absent. Prices are set by either the low-cost competitor or the competitor willing to sell at a loss to keep its plants busy.
High price sensitivity. Consumers are more open to the lowest bid in this market than in others (e.g., healthcare).
Competition is fierce. The market has well-established players in various niches.
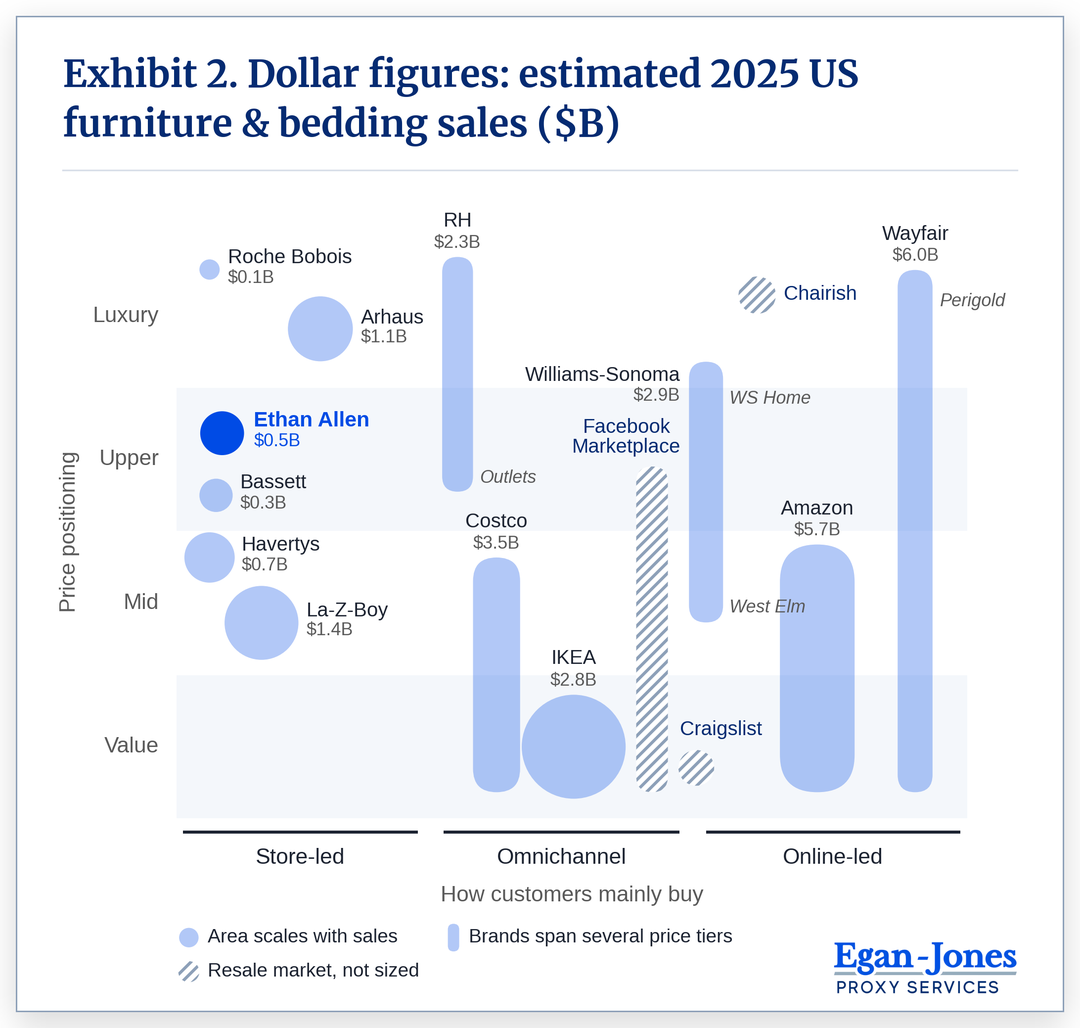
Primary market competition. Firms such as Costco, Wayfair, IKEA, and Amazon are formidable competitors for new furniture.
Secondary market competition. Many consumers discard their furniture short of its natural life, and therefore there is strong competition via secondary markets, such as Facebook Marketplace and Craigslist.
Cost reductions are short-lived. Any equipment that's purchased to reduce cost can be purchased by competitors as well, who in turn can reduce prices for the entire industry.
Lack of necessity. Pinched consumers can often withhold purchasing new furniture and instead hold on to their existing furniture.
Cyclical. Consumers are affected by interest rates and home purchases, both of which have trended against Ethan Allen recently.
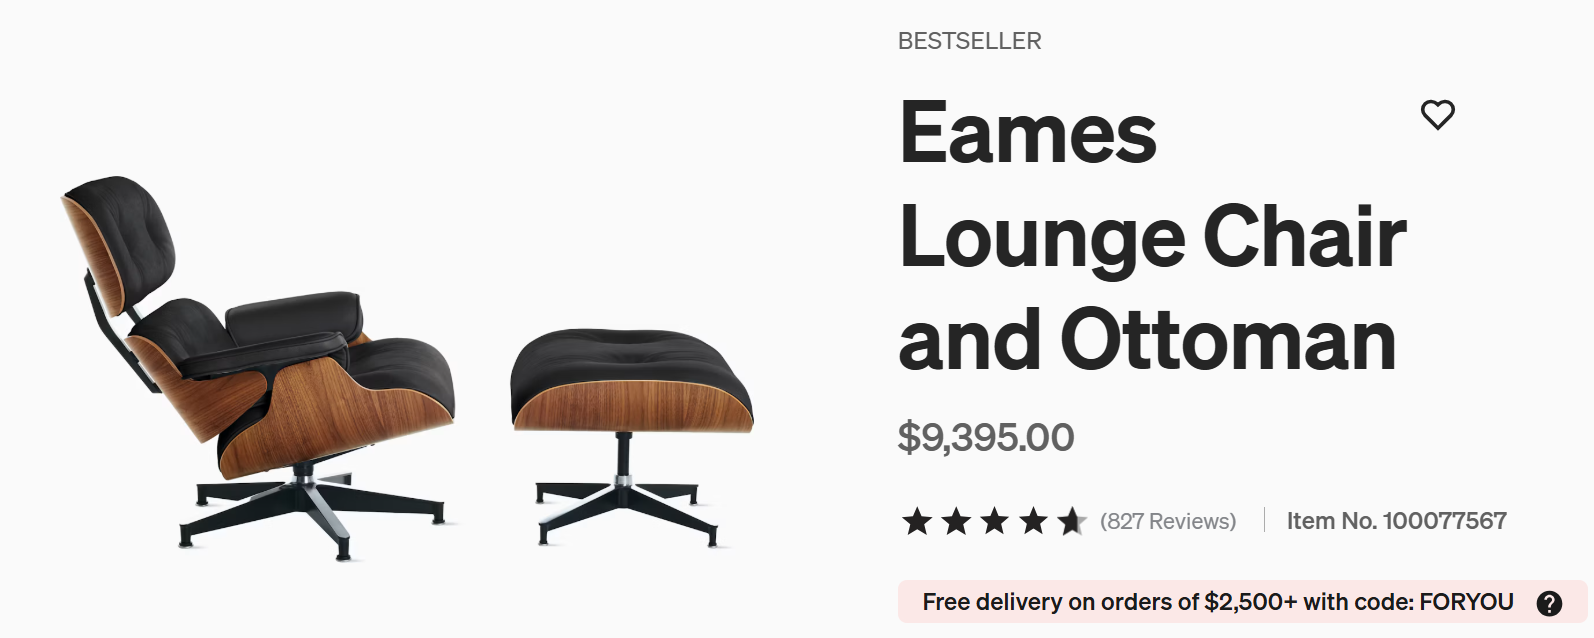
Exception: Note that these rules particularly apply to the low-end and middle portion of the furniture market. At the high end of the market, there may be some exception to these rules, whereby producers can price items based on brand (e.g., the Eames chair, which carries cachet among some buyers). Further, consumers at the highest end of the market are less affected by cyclicality and concerns over necessity.
Ethan Allen position
Ethan Allen has sought to position itself closer to the upper end of the market by focusing on customized furniture. However, it does not qualify as designer furniture. The firm continues to make furniture in North Carolina and offers 172 retail stores (which it calls “design centers”) in North America.
Source: Home News Now 125, estimated 2025 US furniture and bedding sales (June 2026), compiled from SEC filings, retailer input and industry reports; Ethan Allen is trailing 12 months to March 31, 2026. All figures are US only and exclude accessories, rugs and other merchandise (for IKEA US, total revenue was about $5.3B). Price and channel placements are Egan-Jones assessments. Resale platforms do not report furniture sales and are not sized.
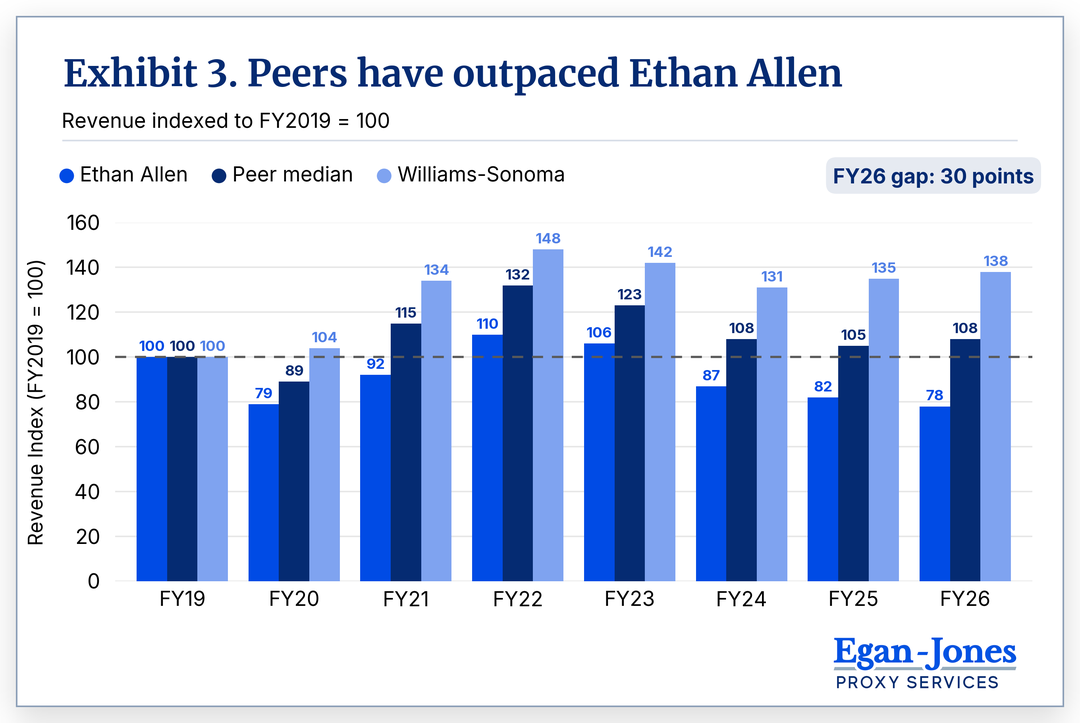
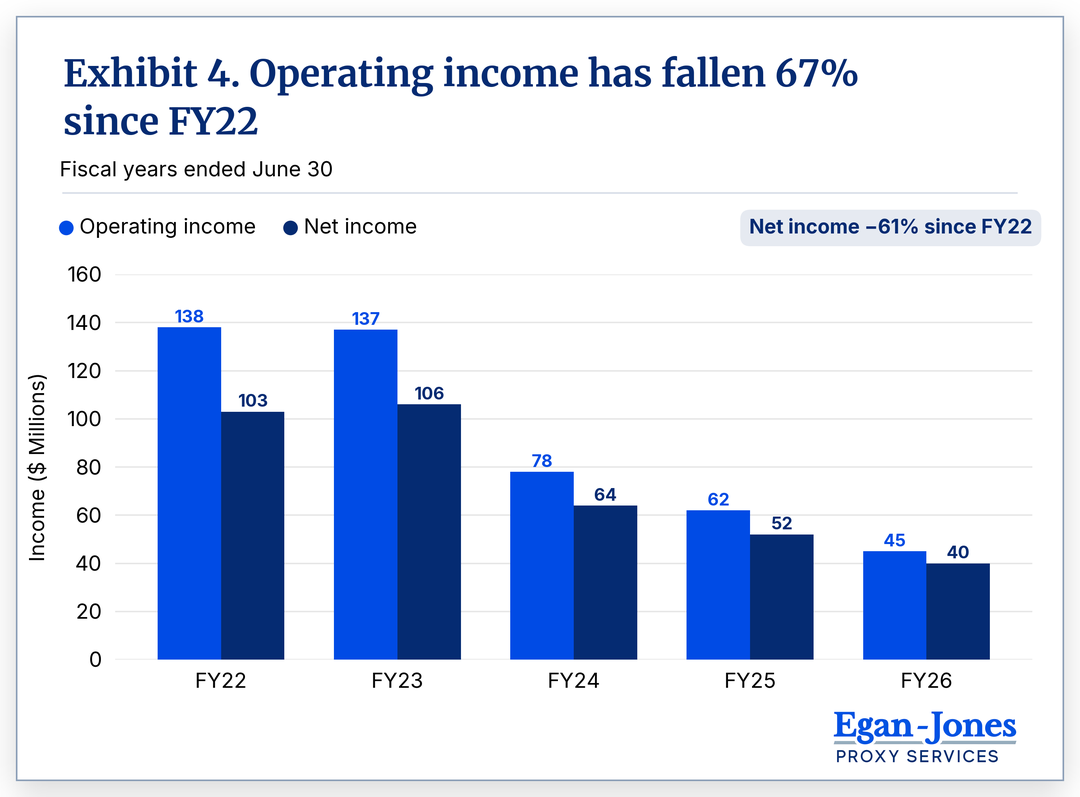
Ethan Allen's sales have fallen four years in a row, unable to recover from the record home buying in 2022 and further hurt by increased interest rates. Its stores and factories are largely fixed costs, so the lost sales cut deeply into profit (Exhibit 4).
Source: SEC XBRL filings. Trailing twelve months revenue for the fiscal quarter ending nearest June 30 of each year, aligned to Ethan Allen's fiscal year (for Williams-Sonoma, the quarter ending in late July or early August). Peer median uses Bassett, Havertys, La-Z-Boy and RH. Williams-Sonoma is shown separately.
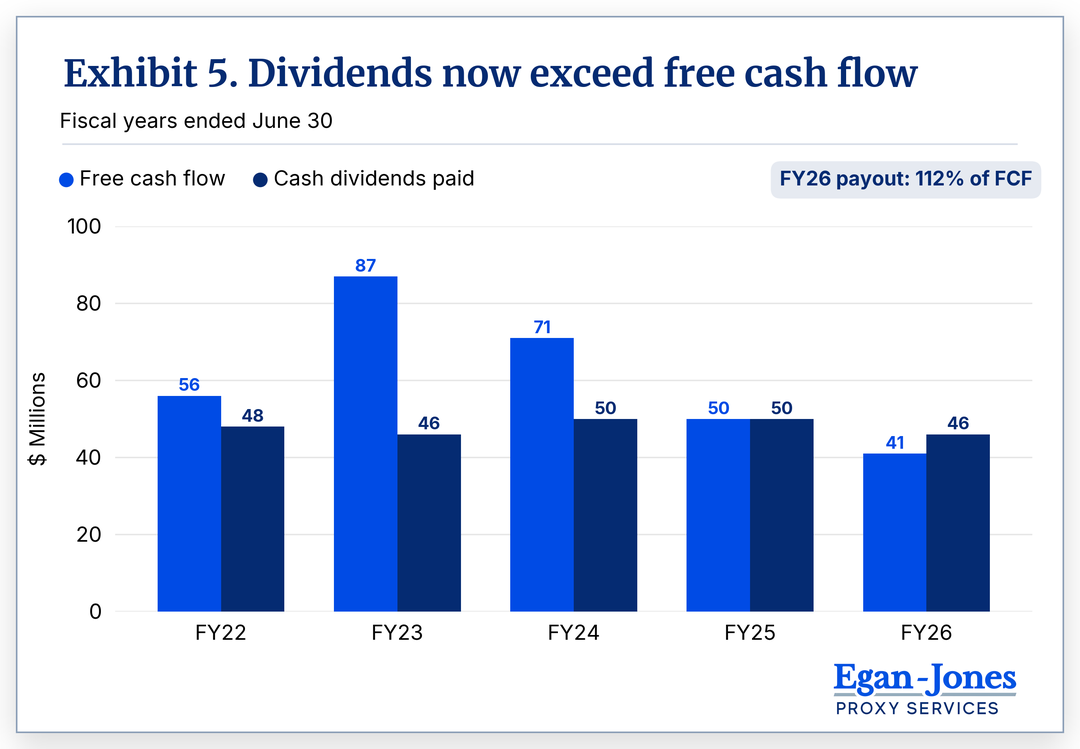
In fiscal 2026 the company paid more in dividends than it generated in free cash flow (Exhibit 5). Two weeks after the contest began, it declared a $3.00 special dividend, about $76 million.4
Source: Ethan Allen Form 10-K filings. Fiscal years end June 30. Excludes the $3.00 special dividend (about $76M) paid in September 2026.
What Williams-Sonoma got right
Though the high end can offer some advantages, it has clearly not worked for Restoration Hardware or Roche Bobois (Exhibit 1). Williams-Sonoma succeeded in implementing the following strategy.
Designs its own products. Most of what it sells is proprietary, so shoppers cannot find an identical item elsewhere and price comparison loses its force.
Built a portfolio of distinct brands. Pottery Barn, West Elm, Williams Sonoma and others each target a different customer and style, so a downturn in one brand does not sink the company.
Led in e-commerce early. It treated online as a core channel rather than an add-on to stores, which let it win new customers at a lower fixed cost than a store-heavy model.
Used customer data to market precisely. Years of purchase history let it target buyers directly instead of discounting to fill showrooms.
Kept its supply chain flexible. Sourcing spread across many countries and suppliers helped it absorb cost shocks and tariffs without cutting prices to keep factories busy.
Dissident Plan
DGB's slate includes the former chief commercial officer of Wayfair, a former customer and retail chief at Neiman Marcus, eBay's former chief strategy officer and the co-founder of the online furnishings marketplace Chairish. Their plan starts with winning new customers online, along with a brand refresh, a new assortment and a store-by-store review, and DGB plans to name an interim CEO on November 4 if it wins.5
Conclusion: To be, or not to be
On the mind of some investors is how best to manage the life and death of their portfolio companies.
Buffett's mills had nothing left to build on. Ethan Allen still has a known brand, its own factories, a design service and a debt-free balance sheet. We believe the DGB nominees are better placed to put them to work, and we recommend voting FOR all five on the WHITE card.
DGB Investment, “Ethan Allen: Building For The Next Century,” investor presentation, October 12, 2026. Peer comparison measured to August 4, 2026 against Arhaus, Bassett, Havertys, La-Z-Boy, RH and Williams-Sonoma.